The $7 Million Janitor
Chapter 12 Interactive Deck • FINC 3501 • University of West Georgia
Can ordinary earnings produce extraordinary wealth? Investigate the story, test the assumptions, and separate financial evidence from an appealing headline.
This is not a portrait of any real individual. It represents everyday people making thoughtful financial decisions.
A Quiet Path to Wealth
Chapter 12 presents Clyde and Suzanne in a story about ordinary earnings and extraordinary wealth. Treat these characters as part of the chapter narrative, not verified portraits of historical people. A striking outcome is the beginning of a financial question, not the answer.
The chapter invites us to investigate the claimed $7.3 million result. What contributions, dates, investment returns, taxes, and fees would have to be true? Discussion 10 asks you to audit the evidence, not simply repeat the story.
Your Decisions Today
Imagine sitting with classmates reviewing career paths, starting salaries, and early investing choices. What trade-offs do you see between spending now versus building a foundation for later?
Commit your thought: One practical habit a college student could start this semester to support long-term wealth.
Example ideas: Automating a manageable amount into a diversified, low-cost investment, living below your means after graduation, or learning to read a prospectus before investing. Small consistent actions matter more than perfect timing.
Everyday Households
Wealth-building is not reserved for high earners. Households that review budgets, automate savings, and align spending with long-term goals can accumulate meaningful assets over decades, without requiring a millionaire salary.
What Could Consistent Saving Produce?
Adjust the inputs to see approximate growth. These are simplified illustrations using compound interest; actual results vary with markets, fees, and taxes.
Enter values and calculate.
Assumes end-of-period contributions and constant return for illustration only.
Contributions vs. Growth
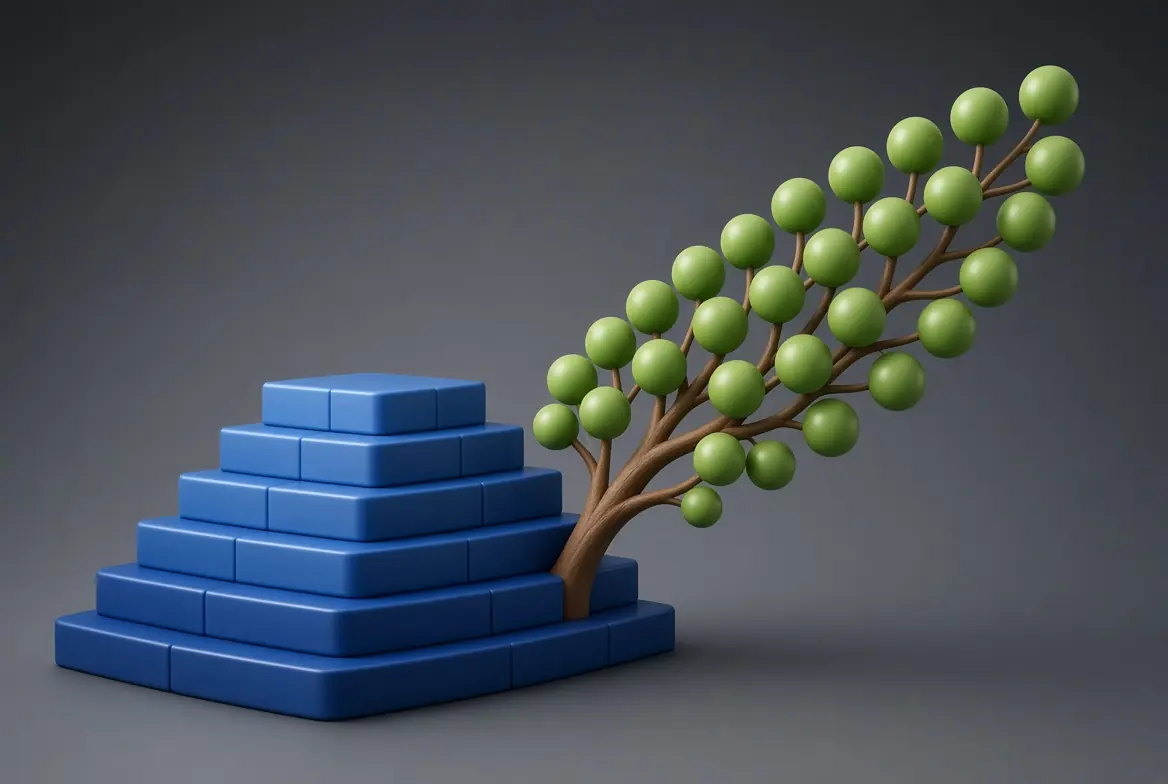
Early contributions have more time to compound. In long horizons, investment growth often exceeds the total amount contributed, the classic “snowball” effect.
Illustration: $200 per month, 8% nominal annual return, compounded monthly; end-of-month deposits. Not a forecast.
When Markets Fall
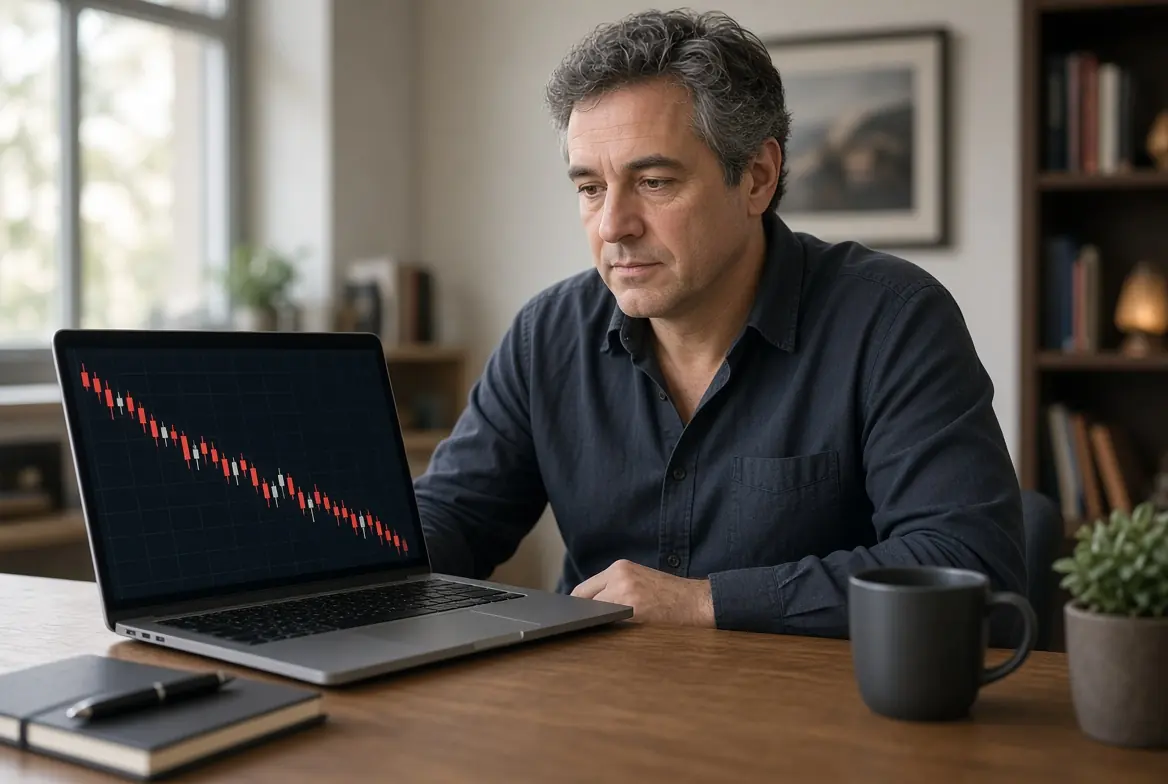
Markets sometimes fall sharply, including in 2008. Staying invested can allow participation in a recovery, but losses can persist and investors need adequate liquidity, diversification, and risk capacity. Selling after a decline realizes the price then available; whether to sell depends on the plan.
If markets drop 20% in a year, what is one reasonable response for a long-term investor?
Thoughtful response: Continue the established plan. A long-horizon investor may continue a suitable diversified plan and rebalance as needed, provided emergency reserves and risk capacity support it. Recovery is not guaranteed for every investment. Borrowing heavily magnifies losses.
Investigate the Numbers
Practice with a separate claim, not the graded Chapter 12 numbers: “Saving $150 a month for 40 years will produce $400,000.” Use the calculator to test this claim at 7% and 9% nominal annual returns, compounded monthly. What assumptions drive the difference?
The method is what matters: identify contributions, dates, rate conventions, dividend reinvestment, inflation, fees, and taxes. Then distinguish a hypothetical model from verified historical evidence. Apply the method independently to Clyde and Suzanne in Discussion 10.
Planning Across Generations
Thoughtful investing can support retirement security and even leave resources for the next generation. A long-term financial plan may support retirement and charitable goals, but outcomes depend on contributions, risk, and actual market experience.
Risk and Expected Return
Chapter 12 emphasizes that higher expected returns generally come with higher risk. Equities have delivered higher long-term returns than bonds or cash, but with greater short-term volatility. Matching risk tolerance and time horizon is essential.
Patient Ownership of Quality Businesses
Chapter 12 uses long-term investing as part of its wealth story. Owning stocks for decades can compound returns, but a concentrated stock portfolio creates company-specific risk. Broad diversification is a separate, important risk-control decision.
Build Your Own Scenario
Use the earlier calculator logic. What monthly amount, starting age, and realistic return assumption produce a result that supports your goals? Record one insight below.
Saved on this device and browser. This is not submitted to CourseDen.
Pitfalls to Avoid
- Trying to time the market
- High fees that erode compounding
- Lifestyle inflation that prevents consistent saving
- Concentration in a single stock or sector
Key Ideas from Chapter 12
- Longer investment horizons give compounding more time, but do not eliminate market risk.
- Modest, consistent contributions can grow substantially.
- Risk and return are linked; align them with your horizon.
- Frugality and patience are practical tools available to ordinary earners.
Before Discussion 10
Discussion 10 is already open. Original post due Friday, October 30; replies due Sunday, November 1 at 11:59 PM. Use the chapter evidence and show your calculations. Do not substitute the separate practice scenario for the assigned case.
What is one change you could make in the next 30 days that aligns with the principles illustrated by this story?
Saved on this device and browser. This is not submitted to CourseDen.
Disciplined Choices Compound
The chapter’s headline wealth figure is a claim to examine, not an outcome guaranteed by ordinary income. Consistent investing, time, and risk management matter, but historical returns and real-life constraints matter too. Your choices about saving rate, asset allocation, and staying the course will shape the path ahead.
Your next move: make one evidence-based financial decision, and explain the assumption behind it.